Subscription Billing Tools and Mobile Fraud Detection: Their Expanding Integration
Uma Fischer · Nov 20, 2026
Subscription Billing Tools and Mobile Fraud Detection: Their Expanding Integration
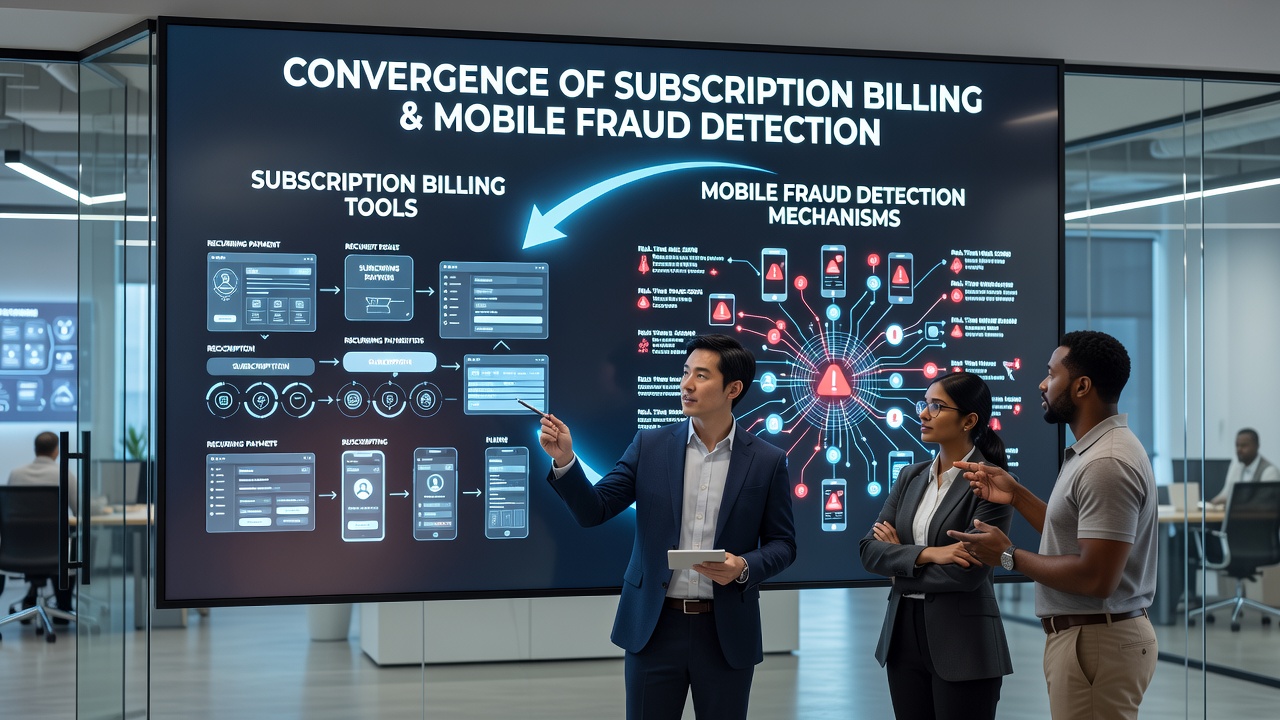
Subscription billing platforms now incorporate mobile fraud detection layers at multiple points in the transaction flow, and this integration has accelerated as companies process recurring charges across smartphones and tablets. Data from industry reports indicate that mobile transactions account for over 70 percent of subscription sign-ups in many sectors, which creates specific vulnerabilities around device fingerprinting, location spoofing, and account takeover attempts. Researchers at various institutions have documented how billing engines feed real-time signals into fraud models, allowing systems to score risk before each recurring charge processes.
Core Components Driving the Convergence
Billing tools manage recurring charges through automated schedules while fraud detection systems analyze behavioral patterns such as login velocity, payment method changes, and device anomalies. When these two functions operate in isolation, delays occur between charge authorization and fraud flagging. Observers note that synchronized platforms reduce that lag by sharing data streams directly, so a suspicious mobile session can trigger an immediate hold on the next scheduled invoice. Studies have shown that organizations linking these systems report fewer false declines because the fraud layer receives context from billing history rather than evaluating isolated events.
Technical Pathways for Data Exchange
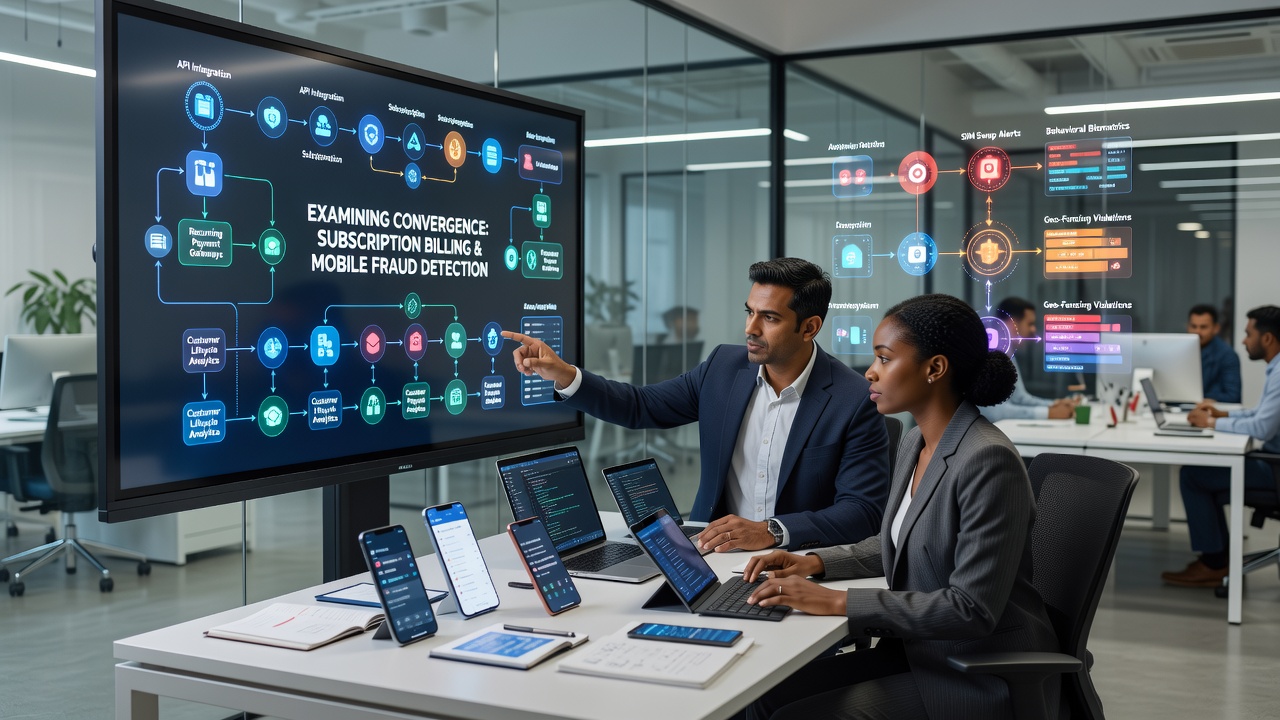
APIs serve as the primary bridge, passing fields like device ID, IP reputation scores, and prior charge success rates between the billing engine and the detection module. Tokenization keeps sensitive card details out of the shared channel while still allowing the fraud system to reference the same tokenized instrument across multiple billing cycles. In November 2026, several payment processors updated their API specifications to include expanded mobile telemetry fields, which enables more granular risk scoring without adding latency to the checkout or renewal process. Companies that adopted these updates early found they could adjust fraud thresholds dynamically based on subscription tenure and average revenue per user.
Regional Regulatory Influences
Compliance requirements differ across jurisdictions yet push similar technical outcomes. The Federal Trade Commission in the United States has issued guidance on recurring billing disclosures that indirectly supports stronger fraud controls, while the European Central Bank has emphasized strong customer authentication for mobile payments. These separate frameworks encourage vendors to embed detection logic inside billing workflows rather than treating fraud as a post-charge review. Australian regulators have likewise updated expectations around digital subscription transparency, prompting local providers to align billing logs with real-time anomaly detection outputs.
Practical Implementation Examples
One media streaming service integrated its billing platform with a mobile fraud engine that monitored SIM swap indicators and rapid device resets. The combined system flagged accounts attempting to change both payment details and registered phone numbers within a short window, reducing unauthorized subscription transfers by measurable margins according to internal metrics shared with industry groups. Another case involved a fitness app provider that linked billing cycle data to location-based risk scoring, allowing the platform to pause renewals when a device appeared in high-risk regions not previously associated with the user. These implementations rely on continuous data loops rather than one-time checks, which keeps the fraud model current as subscriber behavior evolves.
Challenges in Maintaining Accuracy
Balancing fraud prevention against user friction remains a constant calibration task. Overly strict rules can interrupt legitimate renewals for users who travel frequently or switch devices, while lenient thresholds allow more chargebacks. Teams responsible for both billing and security therefore run periodic reviews of model performance, adjusting parameters based on chargeback ratios and customer support ticket volumes. Data indicates that platforms using shared feedback loops between the two systems achieve faster convergence on optimal settings than those maintaining separate review cycles.
Future Trajectory of Integrated Systems
Developments expected beyond November 2026 include deeper use of on-device signals that billing platforms can consume without transmitting raw biometric data. This approach supports privacy regulations while still supplying the fraud layer with enough context to differentiate between genuine device changes and takeover attempts. Industry analysts project continued consolidation of these functions inside single vendor suites, although some enterprises prefer modular connections that let them swap detection providers without reconfiguring the entire billing stack. Either path requires consistent data schemas so that subscription events and fraud signals remain interoperable across updates.
Conclusion
The convergence of subscription billing tools and mobile fraud detection mechanisms reflects ongoing adaptation to the dominance of smartphone-based transactions. Organizations that align these functions through shared APIs, consistent tokenization practices, and regulatory-aware configurations position themselves to handle recurring revenue streams with fewer interruptions from fraudulent activity. Continued refinement of these integrations will depend on the quality of data exchanged and the speed at which models incorporate new mobile threat patterns.